

How to complete a voluntary disclosure form
If you encounter compliance issues as a trustee of your SMSF, utilising the ATO’s SMSF early engagement and voluntary disclosure service may assist in mitigating severe penalties. Proactively approaching the ATO before any investigation demonstrates a commitment to correcting errors and shows that there was no intent to contravene regulations.
Reporting breaches voluntarily
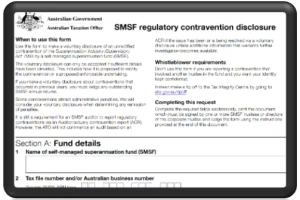
The ATO encourages SMSF trustees to engage with them when they become aware of a contravention of the superannuation rules and regulations (SISA) has been breached. Typically, a contravention first comes to the notice of the fund’s administrator when the fund transactions are being updated during the year, or the financial statements are being prepared after the end of a financial year.
An SMSF trustee voluntarily disclosing an unrectified breach of SISA should use the ATO form found at “SMSF regulatory contravention disclosure” which also includes details as to how you submit the form.
The ATO may not impose penalties on a SMSF trustee if the breach has been rectified prior to the fund’s lodgement of its annual return, and the breach was minor and not material or is rectified soon after.
Your SMSF auditor may still be required to report a breach, but the ATO will not action it if the SMSF has already reported it voluntarily and the breach has either been resolved or is actively working toward a resolution of the breach. The ATO may still impose penalties depending on the materiality of the breach, but they will consider the steps taken by the trustee to rectify the breach. Penalties can include administrative penalties, education requirements, enforceable undertakings, rectification directions, trustee disqualifications, freezing fund assets, winding up the fund and civil and/or criminal penalties.
Favourable interaction between the SMSF trustee and their professional advisers with the ATO during the process will affect the enforcement action imposed and the remission of administrative penalties.
Completing a voluntary disclosure form
It is crucial to engage with your SMSF specialist to ensure the disclosure is made with unemotional, clear and concise language to explain how the breach occurred and how the trustee is planning to resolve the issue including actions to avoid the breach in the future.
Answer disclosure form questions briefly and factually. Be honest, provide evidence, show remorse, and outline steps to prevent future breaches such as seeking advice or attending trustee education. Follow through on your commitments. Don’t ignore requests from the ATO or deadlines and keep in contact with the ATO if needing more time to obtain evidence. Always provide solutions, be prepared to compromise and if required, offer to wind up the fund if unable to resolve the breach satisfactorily.
The ATO will not accept an incomplete disclosure form or one which has not been signed by at least one trustee or a director of the trustee. A tax agent can submit the form on behalf of the SMSF provided they are an authorised contact registered with the ATO.
As per the ATO website
“We expect you to:
- engage with your SMSF professional to create a proposed plan to rectify the contravention
- provide the proposed plan for rectifying the contravention and relevant supporting documentation with your voluntary disclosure
- provide information demonstrating measures have been put in place to avoid similar contraventions occurring again
- actively engage with us throughout the review process
- immediately lodge any outstanding SMSF annual returns
- if necessary, amend SMSF annual returns and or individual income tax returns and pay any tax liabilities that may arise.”
Lodging a voluntary disclosure form vs other actions
The following is a quick guide when SMSF trustees should consider using the ATO voluntary disclosure form or other actions are required.
| Issue | Voluntary Disclosure Service | Other Actions |
| Reporting a contravention by another trustee or director of the trustee and keeping your identify secret | No | Use the ATO service
Making a tip-off to report anonymously |
| You have already received notification of an ATO audit | No | Respond to the ATO questions after seeking the assistance of your SMSF specialist |
| You are unsure if a contravention has occurred | No | Discuss with your SMSF specialist accountant |
| A contravention of SISA has occurred and before the SMSF auditor has to report it to the ATO which is several months after the financial year has ended | Yes | Seek advice from your SMSF specialist |
| Seeking compensation for bad investments due to advice from financial planning firms | No | Consider making a complaint to Australian Financial Complaints Authority # |
| Reporting scams or fraud | No | Seek advice from your SMSF specialist and then Email SMSFStrategicCampaigns@ato.gov.au |
# n.b. complaints about SMSFs are not classed as superannuation complaints but are considered under the general investments and financial advice complaints for non-disclosure or misrepresentation by financial planning firms.